

An article by Mr. Dinh Hong Ky, published in Diễn Đàn Doanh Nghiệp (Business Forum) on September 24, 2026.
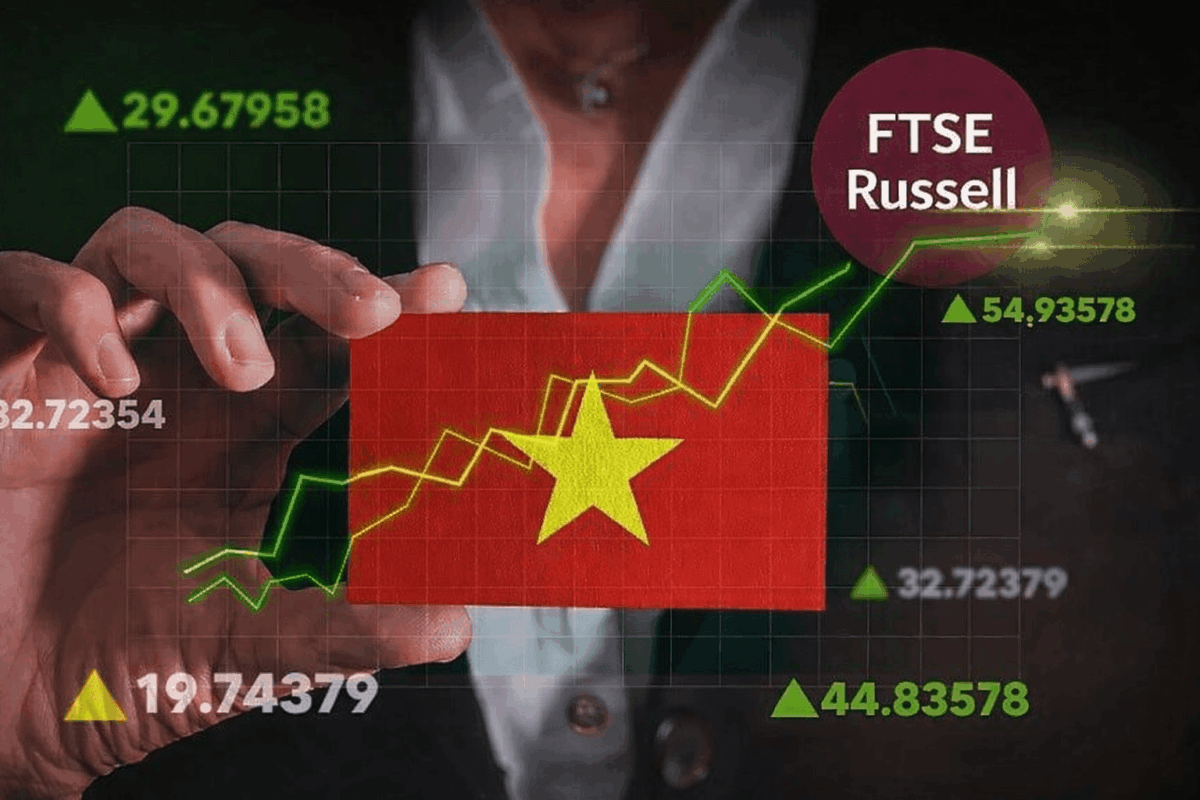
September 21, 2026, marked a significant milestone as Vietnam was officially upgraded by FTSE Russell from a Frontier Market to a Secondary Emerging Market. Just a few days earlier, the U.S. Federal Reserve (Fed) had raised interest rates by 0.25 percentage points, bringing the federal funds rate to 3.75–4%.
Viewed together, these two events highlight a thought-provoking reality: Vietnam’s access to international capital is expanding, while capital worldwide is becoming more expensive and increasingly selective.
In my view, this raises a question more important than how many billions of U.S. dollars might flow into the stock market following the upgrade: Is Vietnam ready to transform new capital inflows into new growth capacity?
From Attracting Capital to Absorbing Capital
FTSE Russell confirmed that Vietnam had met the criteria for classification as a Secondary Emerging Market following a prolonged reform process. The inclusion of Vietnamese equities in FTSE indices will not take place all at once, but will be implemented in four phases from September 2026 to September 2027.
This is more than a change of name in a market classification table. Vietnam now occupies a different position on the asset allocation map of many international financial institutions.
However, the upgrade should not be viewed as the opening of a valve through which money will automatically flow. Capital does not flow simply because of a classification label; it seeks opportunities. Nor is there any guarantee that every dollar entering an economy will automatically generate an equivalent dollar of value.
At a recent conference, I expressed the view that 10 well-prepared projects ready for immediate implementation are more valuable than 100 projects that remain merely at the conceptual stage.
When a company considers investing tens or hundreds of millions of U.S. dollars, it does not need an extensive list of projects. It needs to know whether land is ready, when infrastructure connections will be completed, whether the electricity supply is reliable, how long administrative procedures will take, where the market is, and whether the supply chain can meet the project’s requirements. The gap between expressing interest and committing capital often lies in these very practical questions.
Therefore, after many years of focusing on attracting capital, Vietnam needs to pay greater attention to another concept: capital absorption capacity.
Capital attraction measures the amount of money flowing into an economy. Capital absorption capacity measures the ability to transform that money into productivity, technology, employment, stronger enterprises, and higher value added.
These two measures do not always move together. An economy may receive substantial amounts of credit, foreign direct investment (FDI), or foreign portfolio investment. However, if capital flows primarily into assets, low-value-added industries, or activities in which domestic enterprises have limited participation, an increase in capital does not necessarily translate into a corresponding increase in the economy’s internal capabilities.
Therefore, the question following the market upgrade should not simply be, “How much capital will flow in?” It should also be, “How much value will remain?”
Upgrading the Market, Upgrading Enterprises
There is a reality that must be acknowledged: Vietnam may have achieved a market upgrade, but Vietnamese enterprises will not be upgraded overnight as a result.
As Vietnamese companies enter an environment with larger institutional investors, they will also face higher standards. These investors look beyond revenue or profits in the coming quarter. They are also concerned with cash flow quality, capital efficiency, corporate governance, shareholder rights, sustainable development strategies, and the ability to execute consistently across multiple business cycles.
This presents both pressure and an opportunity for Vietnamese enterprises to transform themselves.
For many years, domestic enterprises have relied heavily on bank credit. However, a company seeking to invest in a technology production line with a 15-year lifespan, an infrastructure project requiring several decades to recover its investment, or a manufacturer pursuing a green transition to meet export standards all require longer-term sources of capital.
The stock market and corporate bond market must gradually assume this role more effectively.
The International Financial Center in Ho Chi Minh City should also be viewed from a similar perspective. Its success should not be measured solely by the number of international banks or investment funds opening offices, but by its ability to connect large, long-term, and diversified sources of capital with those capable of using them efficiently.
If several billion U.S. dollars in new capital merely flow into the stock market, drive up asset prices, and eventually flow out again, the long-term impact on the economy will be limited.
But if that capital enables Vietnamese enterprises to build new factories, invest in research and development (R&D), acquire technology, undertake green transformation, or bring Vietnamese brands to international markets, the outcome will be very different.
Only then will financial capital truly become development capital.
To absorb such long-term capital flows, Vietnam needs not only good projects and strong enterprises, but also a predictable business environment.
Through many years of running businesses and engaging with investors, I have observed that they do not necessarily choose locations with the lowest land prices or the most generous tax incentives.
A high but predictable cost can still be incorporated into a business plan. What is far more difficult to calculate is uncertainty.
An administrative procedure that takes 90 days, but for which a company knows it will receive an answer on the 90th day, can still be factored into its planning.
By contrast, a procedure officially stipulated to take 30 days, but which remains unresolved after six months with no clear completion date, cannot.
During that time, the factory has yet to begin operations, but loan interest must still be paid, machinery continues to depreciate, employees must still receive their salaries, and customers cannot be expected to wait indefinitely.
Vietnam is allocating substantial resources to building expressways, airports, seaports, and digital infrastructure to reduce costs for the economy.
However, if a new road saves a company several hours of transportation time while, elsewhere, the company loses several additional months to an administrative procedure, part of the value created by that infrastructure is effectively lost to delays within the system.
In this sense, transparent institutions, predictable policies, time-bound administrative procedures, and an accountable public administration are also forms of economic infrastructure.
Vietnam cannot control U.S. interest rates, geopolitical conflicts, or changes in global trade. But we can reduce the uncertainties that we ourselves create.
Capital Flows In, Value Stays
Vietnam achieved considerable success in the early stages of its international integration by attracting substantial FDI, expanding exports, and participating more deeply in global supply chains.
Yet that very success now raises a new question: After many years of capital inflows, technology transfers, and the presence of global corporations in Vietnam, to what extent have the capabilities of Vietnamese enterprises grown accordingly?
This is the second half, and also the more difficult part, of the investment attraction challenge.
An FDI-funded factory worth USD 1 billion is clearly a success in terms of attracting capital.
However, if most of its machinery, technology, and raw materials are imported, while Vietnamese enterprises participate primarily in low-value-added activities, the value retained by the economy will be very different from that of a project of the same scale that develops a network of Vietnamese suppliers, transfers technology, trains engineers, and fosters the growth of domestic enterprises.
The same principle applies to capital markets.
One billion U.S. dollars spent buying and selling shares on the secondary market has a different economic significance from one billion U.S. dollars raised by enterprises to increase their capital, invest in technology, and expand into global markets.
Both represent capital inflows, but their potential to generate new productive capacity is very different.
Therefore, Vietnam’s competition in the coming years will not simply be about attracting more capital. It will be about attracting higher-quality capital and, more importantly, ensuring that every dollar invested generates greater value for the economy.
We need capital flows that bring technology, management expertise, market access, and the ability to connect Vietnamese enterprises with higher-value segments of global supply chains.
However, this will only be meaningful if Vietnam also has enterprises with sufficient capabilities to absorb technology, become suppliers, participate in joint product research, and ultimately enter international markets independently.
If high-quality capital flows into the country but domestic enterprises lack the capacity to absorb it, Vietnam may still achieve rapid growth, and exports may continue to set new records. However, the gap between the FDI sector and domestic enterprises will remain difficult to narrow.
And this is perhaps where we need to change the way we define success.
Two decades ago, Vietnam’s success was measured largely by its ability to attract capital into the economy: how much FDI was registered, how many new projects were launched, and how much investment capital was disbursed.
These figures remain important. However, over the next two decades, another measure must be added: How much of the value generated by these capital inflows can we retain?
That value may take the form of a Vietnamese enterprise becoming a tier-one supplier to a global corporation, a patent developed in Vietnam, a team of engineers mastering new technology, a Vietnamese brand capable of acquiring a company overseas, or simply a new generation of domestic enterprises with higher productivity and stronger management capabilities than the generation before it.
The market upgrade gives Vietnam access to a larger pool of global capital.
But our position in this new arena will not be determined by how much money flows into the country. It will be determined by what remains in Vietnam after that capital has passed through: a larger asset market, or stronger enterprises, better technology, and a more productive economy.
That is the most challenging upgrade of all.
Original article published in Diễn Đàn Doanh Nghiệp (Business Forum): https://diendandoanhnghiep.vn/sau-nang-hang-dieu-gi-o-lai-10184914.html